When an online business or B2B merchant starts accepting digital payments in India, the most straightforward setup often appears to be sharing a static UPI QR code or bank Virtual Payment Address (VPA).
At modest volumes -5 to 10 orders a day the operational workflow feels manageable:
- The customer pays via UPI and enters their 12-digit Unique Transaction Reference (UTR) or uploads a payment screenshot.
- An operations team member opens the business bank account or SMS alerts.
- They search for the matching 12-digit reference number.
- Once verified, the order status is updated to "Paid," and the warehouse dispatches the package.
Because this method incurs zero gateway setup complexity and zero transaction fees, it often looks like a cost-free solution.
However, as order volume scales to dozens or hundreds of transactions daily, manual UTR verification ceases to be free. It turns into an operational bottleneck that quietly drains engineering bandwidth, inflates customer support costs, slows fulfillment, and introduces financial reconciliation blind spots.
1. What Is a UTR and Why Does Manual Verification Break Down?
A Unique Transaction Reference (UTR) is a 12-digit alphanumeric or numeric identifier generated by the banking switch (NPCI/NEFT/RTGS) to uniquely identify an individual financial transfer across the banking ecosystem.
[Customer Payment App] ──> Generates 12-digit UTR ──> [Core Banking System]
                                                              │
                                                              ▼
[Merchant Operations]  <── Manually Searches Statement <──────┘
The fundamental breakdown occurs because a static UTR carries financial data, but zero application context.
When a payment lands in a business account via a static QR or standard VPA, the bank statement typically reflects only:
- The 12-digit UTR
- The remitter's name (which often does not match the customer's account name on your store)
- The timestamp
- The transfer amount
The statement contains no cart ID, no invoice reference, and no SKU details. Connecting that raw bank entry back to an open order requires human intervention to cross-reference multiple screens.
2. The Four Hidden Operational Costs
Cost 1: Fulfillment Latency and Lost Customer Lifetime Value
Modern digital commerce runs on speed. When a customer pays online, they expect instant confirmation.
With manual UTR verification:
- Orders placed outside business hours (late evenings, weekends) sit in a pending queue until staff check the bank portal next morning.
- Digital goods, course access, or time-sensitive software licenses cannot be provisioned instantly.
- Order dispatch is delayed by several hours, increasing post-order anxiety and cart cancellation rates.
Cost 2: The Support and Operations Labor Tax
Manual verification scales linearly with transaction volume. If checking one UTR, verifying the amount, and updating an internal order takes 2 minutes:
| Daily Transactions | Time Spent Daily | Monthly Labor Hours | Estimated Operational Impact |
| 25 orders | ~50 minutes | ~25 hours | Manageable by existing staff |
| 100 orders | ~3.3 hours | ~100 hours | Requires half of a dedicated role |
| 300 orders | ~10 hours | ~300 hours | Requires 2 full-time operations agents |
As volume grows, businesses end up paying full-time salaries solely for staff to copy and paste 12-digit numbers between banking tabs and order management systems.
Cost 3: Vulnerability to Screenshot Fraud and Typos
Manual verification introduces two major sources of human error:
- Typographical Errors: Customers frequently mistype 12-digit numbers (swapping an
8for a0or transposing digits), triggering unnecessary support back-and-forth. - Fabricated Payment Receipts: Readily available receipt generators allow bad actors to produce convincing fake payment screenshots with matching amounts and fabricated UTRs. Operations teams processing hundreds of orders per day under time pressure routinely miss forged reference numbers.
Real Risk: An unverified UTR marked as "Paid" creates inventory leakage
that is only caught weeks later during monthly accounting closes.
Cost 4: Month-End Financial Reconciliation Discrepancies
When finance teams prepare monthly Profit and Loss statements and GST filings, manual logs invariably contain discrepancies:
- Payments received with no matching order (orphaned funds).
- Orders fulfilled where the payment failed or reversed at the bank level.
- Timing variances between order creation dates and bank settlement timestamps.
Resolving these variances requires tedious ledger audits, pulling historical CSV dumps from multiple banking portals, and manually matching transaction line items.
3. The Math: Manual Verification vs. Automated Orchestration
Consider an e-commerce merchant processing 3,000 orders per month (averaging 100 orders/day) with an average order value of ₹1,200.
Manual Verification Model:
- Staff Time (100 hours/month @ ₹250/hr): ₹25,000
- Support Tickets & Overhead (Disputes, typos): ~₹10,000
- Fraud / Misplaced Orders (0.5% leakage): ₹18,000
Total Hidden Monthly Cost: ~₹53,000 / month
The operational overhead easily exceeds the perceived savings of bypassing automated payment infrastructure.
4. How Modern Payment Workflows Replace Manual UTR Matching
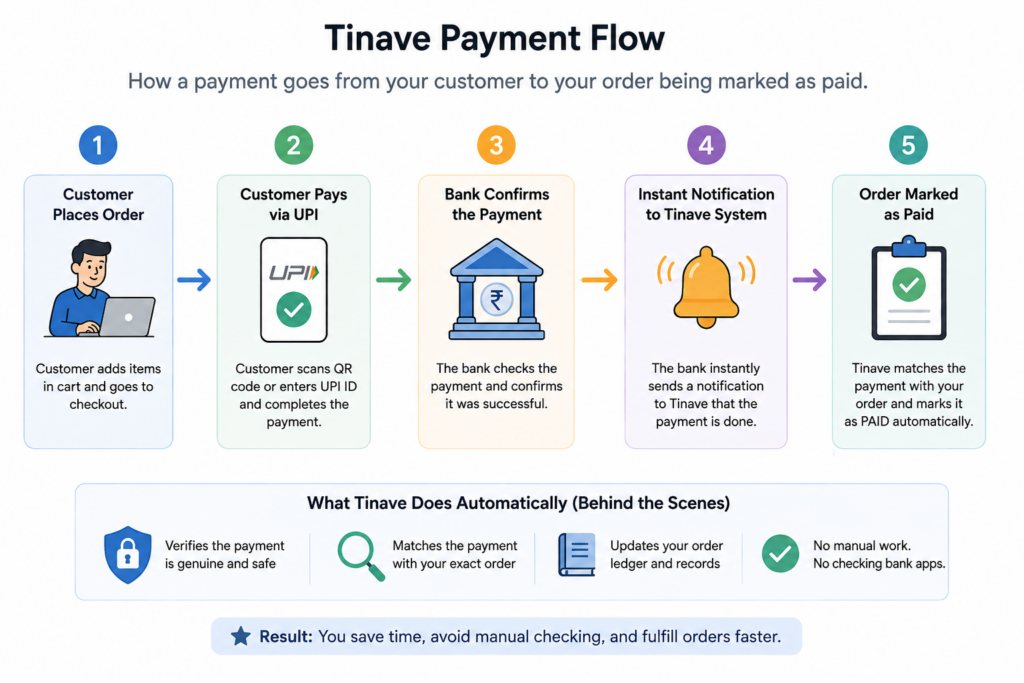
Eliminating manual verification does not require adding friction or exorbitant transaction fees. It requires transitioning from unstructured static transfers to context-aware payment workflows.
1. Dynamic UPI QR & Intent
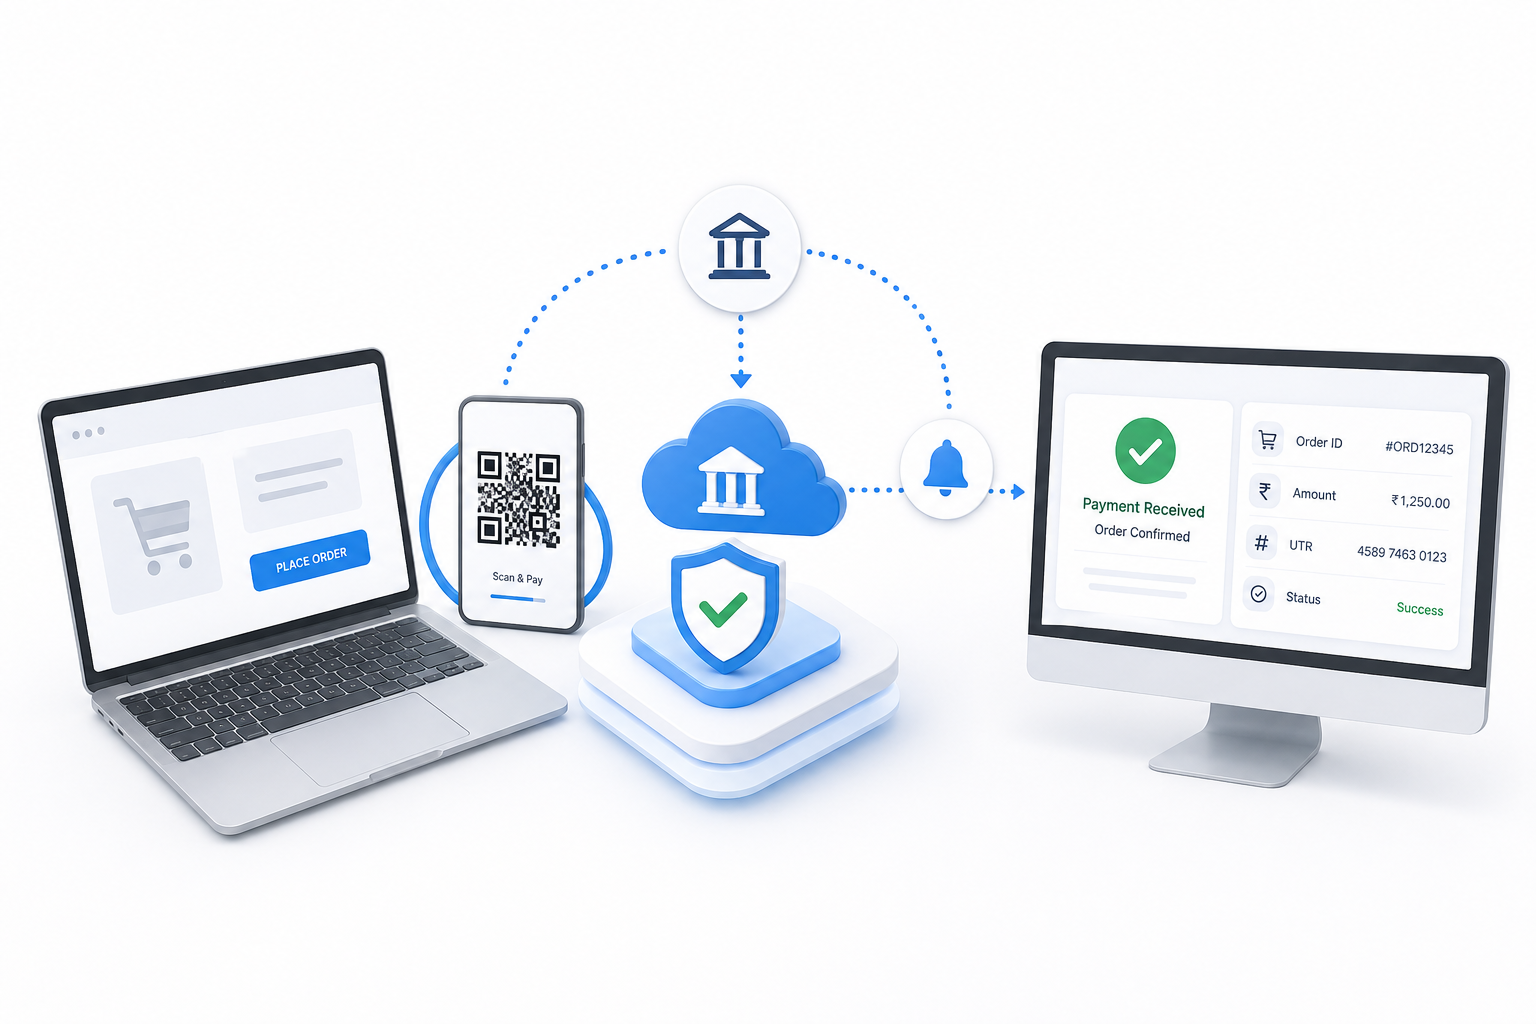
Instead of a static QR code where the customer types the amount, dynamic generation embeds the exact cart total and a unique transaction reference (tr) directly into the payload. The customer cannot alter the payable amount, eliminating partial payment disputes.
2. Server-to-Server Webhook Callbacks
The moment the acquiring bank clears the payment, a cryptographically signed webhook is dispatched to the merchant application. The order status updates programmatically within milliseconds triggering warehouse packing or digital access with zero manual oversight.
3. Programmatic Three-Way Reconciliation
The payment infrastructure automatically logs the Order ID, the Transaction Token, and the underlying Bank UTR into an immutable digital record. Month-end reconciliation shifts from a multi-day spreadsheet exercise to a one-click audit export.
Moving Beyond Spreadsheets
Manual UTR matching is a common milestone for businesses taking their first steps in digital commerce. However, treating manual verification as a permanent strategy creates an invisible ceiling on operational capacity.
Automating transaction verification is not merely about convenience; it is about building resilient operational plumbing that lets your team focus on product development, customer experience, and sustainable growth.